Wealth & investment
Set a clear purpose, risk framework, diversification approach and review process for the capital you have built.
See how investment decisions are coordinatedAMGENT helps business owners, UK expats, professionals and retirees coordinate superannuation, investments, retirement income, succession, insurance and estate planning. You get a clear view of what matters now, what depends on it and what to do next.
 Start with the decision that matters now.
AMGENT maps the financial, family and business consequences around it before recommendations begin.
Whether the trigger is a business sale, UK pension decision, retirement date, career change or family transition, AMGENT starts with the event and then maps the financial decisions connected to it.
Coordinate personal wealth, sale or succession options, protection and life after the business.
See how we help business owners plan succession
Understand transfer considerations, Australian super, retirement income, tax coordination and estate issues.
Explore UK pension and cross-border advice
Bring investments, super, protection and estate priorities into one manageable plan.
See how professionals can simplify the plan
Coordinate cash flow, super, investments, insurance, practice ownership and long-term priorities.
See financial planning for medical professionals
Connect income, super, investments, spending, family support and estate intentions.
Plan your transition to retirementAMGENT can advise across six core areas, but the work is scoped around how those areas interact in your circumstances — not as separate solutions competing for attention.
Set a clear purpose, risk framework, diversification approach and review process for the capital you have built.
See how investment decisions are coordinatedWork out how super, investments, property and business proceeds can support spending through retirement.
Plan your transition to retirementReview contributions, pensions, investment settings, liquidity, trustee responsibilities and beneficiary arrangements.
Review your superannuation strategyIdentify the financial impact of death, disability or time away from work across your family and business.
Review business and personal protectionGet help with the financial decisions around a TPD claim, including superannuation tax components, payout choices and investment planning after payment.
Get TPD claims advice and supportConnect legal intentions with super, ownership, liquidity, retirement and the practical transfer of business and family wealth.
Plan estate and business succession decisionsThe figures below are drawn from case studies published by AMGENT and show the type of coordination involved in real client situations. They are historical examples only, not forecasts or promises of future outcomes.
In a published SME exit case study using small business CGT concessions and coordinated planning.
Business owner case studyFeatured in AMGENT's published British expat case study, alongside cross-border and estate planning.
UK expat case studyA published medical-professional case study describes investments, insurance and estate matters being coordinated together.
Professional case studyComplex client decisions are handled with direct senior adviser involvement and coordinated specialist input where required.
Boutique advice modelAMGENT keeps one senior adviser responsible for understanding the wider position while accountants, lawyers and other specialists contribute within their own areas. The aim is fewer gaps, fewer conflicting assumptions and clearer ownership of the next decision.
See how the advice process worksYou know who is responsible for understanding the history behind the plan and the decision in front of you.
Business, super, retirement, protection, estate and cross-border issues are considered together where relevant.
AMGENT can coordinate with your accountant, lawyer and insurance specialists rather than leaving you to connect separate conversations yourself.
The plan can be reviewed as markets, legislation, family circumstances and business priorities change.
Whether a claim is being prepared or a payout is approaching, AMGENT can help organise the financial questions that sit around the insurance process. That may include understanding superannuation tax components, comparing payout options, planning cash needs and building an investment approach after payment.
From the 2026-27 income year, the Division 296 framework uses a $3 million large super balance threshold and a $10 million very large super balance threshold. The AMGENT estimator provides an educational threshold screen and, when statutory earnings components are available, an indicative rate calculation.
AMGENT calculators and checklists help you test assumptions, organise information and identify gaps before personal advice begins. Each tool is explicit about what it can calculate and what still needs professional judgement.
Run 1,000 market scenarios to test how retirement assets, spending, inflation and return sequences interact.
Run the retirement simulationOrganise property, debt, currency, pension and estate questions across the UK and Australia.
Open the UK expat checklistPrepare valuation, succession, tax coordination, retirement and family questions before an exit.
Open the business exit checklistUse DOB and dates to estimate how the disability formula may change tax-free and taxable components.
Estimate TPD tax componentsScreen the relevant superannuation thresholds and see an indicative additional-tax calculation when inputs are available.
Understand Division 296Highlight missing information and prompt useful questions to discuss with an adviser before retirement decisions are finalised.
Check retirement readinessEach stage is designed to make the scope, fee basis, responsibilities and next action clear — from the first conversation through implementation and later review.
A complimentary conversation about your goals, timelines, concerns and the decision that brought you to AMGENT. No obligation.
AMGENT identifies the areas that need attention and agrees the scope of advice with you before personal recommendations begin.
Where relevant, AMGENT works alongside your accountant, lawyer and insurance specialists so responsibilities are clear.
Reviews and adjustments keep the plan connected as circumstances, markets and rules change.
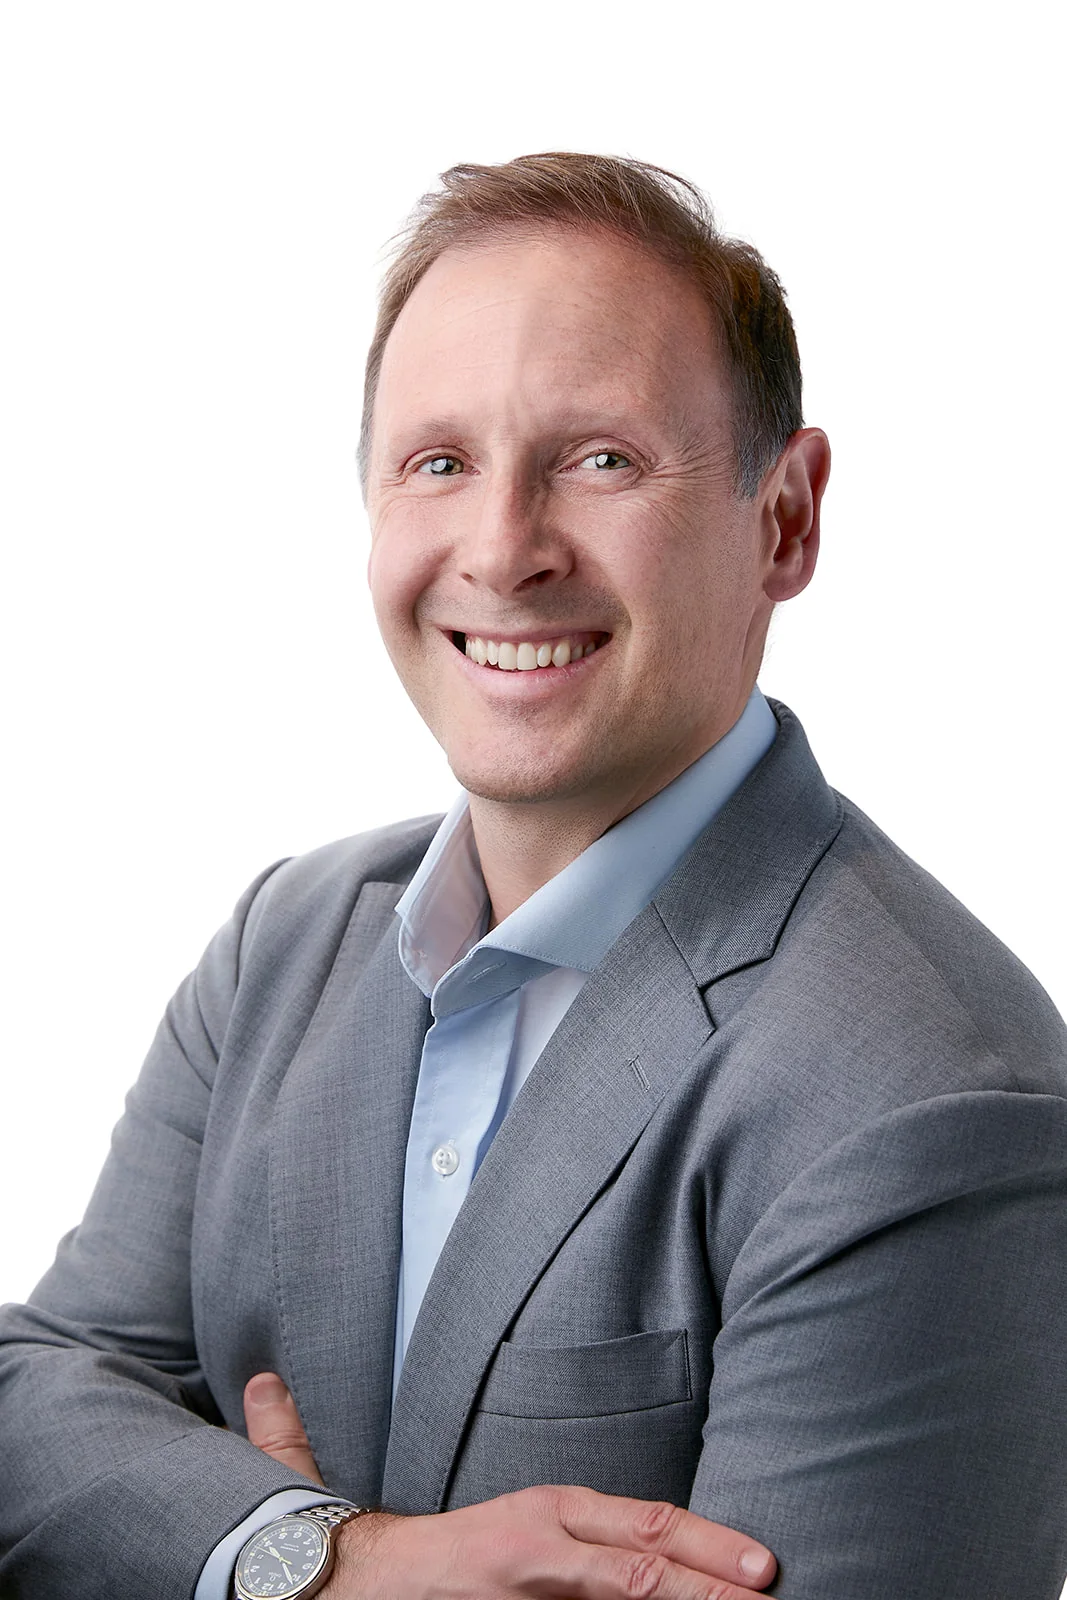
Benjamin, known as Ben, brings more than 25 years of experience across domestic and international financial markets, superannuation and financial advice. His international perspective includes time in the US and Japan, work in London's financial markets and a career built in Australia.
AMGENT was built around direct senior adviser access. Ben keeps the central advice relationship and coordinates with accountants, lawyers and insurance specialists when their expertise is required, so the wider plan is not left fragmented across separate conversations.
Selected feedback currently published by AMGENT. Individual experiences, advice needs and outcomes vary.
“After my father passed away, AMGENT supported my family through the transfer of the estate and the family business, updated our SMSF, and helped secure our future, enabling my mother to retire with peace of mind.”
Karen C
“As a British expat, I was anxious about transferring my pension. AMGENT explained every step and gave me clarity I couldn’t find elsewhere.”
Andrew Bell
“With multiple advisors giving me conflicting advice, I felt overwhelmed. AMGENT created one clear strategy - now I know my wealth and legacy are protected.”
Rob Lewis
General educational articles that explain the financial decisions behind business succession, retirement, UK pensions, superannuation, protection and estate planning.
Five practical checks to compare advisers by qualifications, scope, fees, communication and ongoing support.
Read article
Is $1 million enough to retire at 60? The answer depends on spending, housing, super access, other assets, Age Pension eligibility and how your portfolio is structured.
Read article
A practical guide to adviser fees, one-off versus ongoing advice, and the questions that help you judge whether the service is worth paying for.
Read articleWhether the issue is a business transition, UK pension, retirement date, TPD claim or a set of disconnected advisers, the first conversation is used to identify what depends on the decision and what should happen next.