UK expats · Pension transfer guide · Updated for 2026
UK Pension Transfer to Australia: The 2026 Guide for British Expats
A UK pension transfer to Australia can bring your retirement savings into one system and one currency, or it can be a costly mistake. This guide sets out the 2026 rules on both sides: eligibility, QROPS, the 25% overseas transfer charge, ATO tax on growth, contribution caps, and when keeping your pension in the UK is the better choice.
Can you transfer a UK pension to Australia?

Moving a UK pension to Australian super is often possible, but not every pension and not at every age.
| UK pension type | Can it be transferred to Australia? |
|---|---|
| Personal pension, SIPP or workplace defined contribution (DC) pension | Usually, if you meet the age rules and the receiving fund is a QROPS |
| Funded defined benefit (final salary) scheme | Possibly. A transfer value is required, and UK regulated advice is mandatory above £30,000 |
| Unfunded public service schemes (for example NHS, Teachers', Police, Civil Service, Armed Forces) | Generally no. Since 2015, UK rules stop members transferring these schemes to a scheme offering flexible benefits, which includes Australian super |
| UK State Pension | No. It can't be transferred, but you can usually claim it while living in Australia |
Age matters on both sides. HMRC's "pension age test" means a recognised overseas scheme must not pay benefits to members under 55 (57 from 6 April 2028), except for ill health. In Australia, funds can generally accept member contributions, including foreign transfers, only until 28 days after the end of the month you turn 75. In practice, the window is about 55 to 74.
QROPS in Australia: which super funds can accept a UK pension transfer?
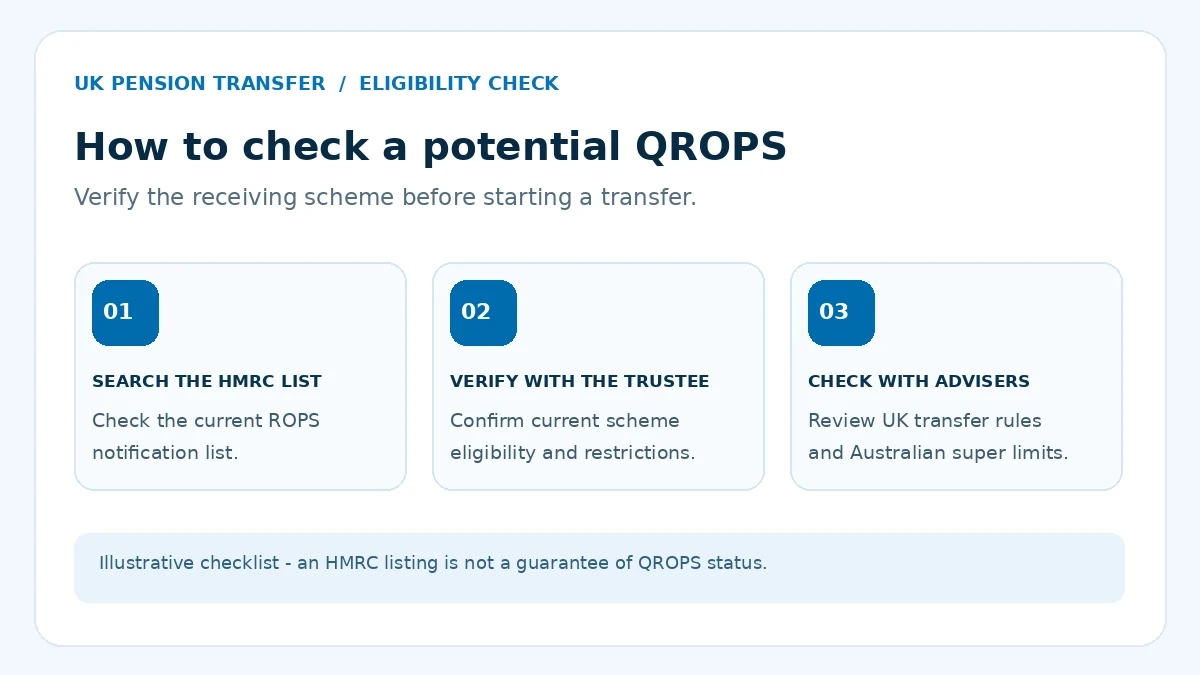
A UK pension can only be transferred free of UK unauthorised-payment tax to a qualifying recognised overseas pension scheme (QROPS). HMRC publishes a recognised overseas pension schemes (ROPS) notification list, but it states that appearing on the list is not a guarantee the scheme is a ROPS. If a transfer goes to a scheme that turns out not to qualify, gov.uk warns the member will pay tax of at least 40% of the fund value.
Large funds must allow early release in limited Australian circumstances, such as severe financial hardship, which fails the UK pension age test. When we reviewed HMRC's list in October 2026, it held about 2,400 Australian scheme names. Most appear to be SMSFs, and we couldn't find the large industry funds on it. The list changes, so check it yourself.
Your realistic options are usually:
- A QROPS-compliant SMSF: the deed must include the UK age restriction and the trustees notify HMRC. You take on trustee duties, set-up and audit costs, and HMRC reporting. See SMSF advice.
- A public-offer fund on the list: check its PDS, fees, investment options and minimum age.
- Not transferring: keeping the pension in the UK is a legitimate outcome.
Also note: the ATO says the Australian fund must have your tax file number within 30 days of the transfer, or return the money.
UK pension transfer tax: the 25% overseas transfer charge and its exemptions
The overseas transfer charge (OTC) is a 25% UK tax on transfers to a QROPS unless an exclusion applies. The key exclusion here is being resident in the same country as the QROPS, so an Australian resident transferring to an Australian QROPS (HMRC PTM102200).
Four rules catch people out:
- The 5-year clawback. If you relied on the residence exclusion and leave Australia within the "relevant period" (the transfer date to the next 5 April, plus five full UK tax years), the 25% charge can apply after the event.
- The overseas transfer allowance. Even exempt transfers are taxed at 25% on any amount above your available overseas transfer allowance, which is usually £1,073,100.
- The 30 October 2024 Budget changes. The exclusion for transfers to QROPS in the EEA and Gibraltar was removed for transfers on or after 30 October 2024. From 6 April 2025, EEA schemes must meet the same ROPS conditions as the rest of the world (HMRC policy paper).
- Paperwork. If the UK scheme doesn't get the required information from you within 60 days, administrators are told to deduct the charge automatically.
Australian tax on a UK pension transfer
Australia doesn't tax the amount your pension was worth when you became an Australian tax resident. It taxes the growth since then, known as applicable fund earnings (section 305-75 of the Income Tax Assessment Act 1997). See the ATO's foreign super transfer guidance.
- The 6-month window. If you transfer within six months of becoming an Australian tax resident, or of your foreign employment ending, none of the transfer is treated as applicable fund earnings.
- After six months: the growth is taxed at your marginal rate. Alternatively, if you transfer your whole UK interest directly to an Australian complying fund, you can elect in writing (by the time you lodge that year's return, and irrevocably) to have the fund pay 15% on some or all of it.
- Contribution caps. The rest of the transfer generally counts as a non-concessional contribution. Any amount you elect to have taxed in the fund doesn't count towards the caps.
| 2026–27 figure (ATO) | Amount |
|---|---|
| Non-concessional contributions cap | $130,000 a year |
| Bring-forward (total super balance under $1.84m at 30 June 2026) | Up to $390,000 over 3 years |
| Bring-forward (total super balance $1.84m to under $1.97m) | Up to $260,000 over 2 years |
| Non-concessional cap is nil | Total super balance $2.1m or more (the general transfer balance cap) |
Division 296 tax started on 1 July 2026: an extra 15% on earnings linked to total super balances above $3 million, plus 10% above $10 million (ATO). Foreign super interests are excluded, so moving a large UK pension into super can bring it into scope. Try our Division 296 calculator.
Defined benefit pensions and the £30,000 advice rule
If your UK benefits are safeguarded (for example a final salary pension or guaranteed annuity rate) and worth more than £30,000, section 48 of the Pension Schemes Act 2015 requires advice from a UK Financial Conduct Authority (FCA) authorised adviser with pension transfer permission. The scheme must check this before paying out (gov.uk). The UK Pensions Regulator's guidance says it believes it is likely to be in the best financial interests of most members to stay in their defined benefit scheme.
What this means for you: a defined benefit transfer normally needs two advisers. The UK FCA-authorised adviser advises on giving up the guarantee. An Australian adviser advises on the receiving fund, tax, caps and retirement income. AMGENT advises under an Australian licence and provides the Australian side. We don't give the UK regulated advice, but we coordinate with the UK adviser.
Should you transfer or keep your UK pension?
There's no default answer. These are the trade-offs we test with clients.
| Consideration | Transferring to Australian super | Keeping the pension in the UK |
|---|---|---|
| Tax on withdrawals | Benefits from a taxed Australian fund are generally tax-free from age 60 | Under the UK–Australia tax treaty, pension income paid to an Australian resident is generally taxable in Australia at your marginal rate |
| Currency | Assets and income in Australian dollars, matching your spending | Exposure to GBP, with exchange-rate movements on every payment |
| Guarantees | Defined benefit guarantees and indexation are given up | Guaranteed, often indexed, income is kept |
| Contribution caps and limits | Limited by the non-concessional cap, bring-forward, total super balance and age 75 | No Australian cap issues |
| Large balances | Counts towards your total super balance and Division 296 | Excluded from Division 296 (as a foreign fund interest) |
| UK inheritance tax | Depends on your circumstances. Get UK tax advice | From 6 April 2027, most unused pension funds and death benefits fall within the estate for UK IHT. Whether this affects you depends on your UK IHT status |
| Moving again | The 5-year OTC clawback may apply if you leave Australia | Flexible if you might return to the UK |
A transfer is more likely to suit you if you hold a DC pension or SIPP with no guarantees, intend to stay in Australia, are 55 to 74 with room under the caps, and want one currency and simpler estate administration.
Keeping it in the UK is more likely to suit you if your pension has valuable guarantees, you might move again within the clawback period, your balance is near the caps or Division 296 threshold, or the Australian set-up costs outweigh the benefits.
The UK State Pension is separate. It can't be transferred and, if you live in Australia, it isn't increased each year (it's "frozen"). From 6 April 2026, most people abroad can no longer pay voluntary Class 2 National Insurance, and new Class 3 applicants need 10 years of UK residence or contributions (gov.uk). Check your State Pension forecast before deciding whether to fill gaps.
Timing: before you arrive, the first six months, and later
| When | What to consider |
|---|---|
| Before you move | Gather statements and transfer values. The OTC residence exclusion relies on being Australian resident when you transfer |
| First 6 months as a tax resident | No applicable fund earnings, but you must meet the age rules, have a QROPS ready and fit within the caps |
| After 6 months | Growth since arrival is taxable. Weigh the 15% fund election against your marginal rate and plan around bring-forward |
| Approaching 75 | Leave time for UK providers to process the transfer before the cut-off |
| Lump sum or drawdown | In super you can keep the money invested, start an account-based pension or take lump sums once you meet a condition of release. Compare this with UK drawdown taxed in Australia |
How to transfer a UK pension to Australia: step by step
- Find every UK pension (use the Pension Tracing Service for lost ones). Request a statement and transfer value, and confirm whether any benefits are safeguarded.
- Confirm eligibility. Check your age, the scheme type (unfunded public service schemes can't move to super), your residence and your remaining overseas transfer allowance.
- Take UK regulated advice if required. For safeguarded benefits over £30,000, get advice from an FCA-authorised adviser and check them on the FCA Register.
- Get Australian advice on whether to transfer, which QROPS, the 6-month window, the earnings election, caps and Division 296.
- Choose or establish the QROPS. For an SMSF, that means a compliant deed and HMRC notification. Confirm status with the trustee.
- Complete the UK transfer forms, including the OTC exclusion information, and give the Australian fund your TFN.
- Make the election if relevant. Lodge the ATO election form with your fund before you lodge that year's tax return.
- Report and review. Declare any earnings not elected into the fund, keep records for the relevant period, and update nominations and your estate plan.
Worked example (illustrative only)
This example is hypothetical, simplified and rounded. It isn't a forecast or a recommendation, and real calculations under section 305-75 can be more complex.
Helen, 58, moved from Manchester to Melbourne and became an Australian tax resident on 1 March 2024. Her UK SIPP has no guarantees and was worth A$380,000 then and A$440,000 at transfer in October 2026 (assumed exchange rates). Her Australian super balance at 30 June 2026 was A$300,000, and she has never used the bring-forward rule.
- UK side: she lives in Australia and the receiving SMSF is an Australian QROPS, so the residence exclusion applies. The amount is well under the £1,073,100 allowance. If she became resident elsewhere before 5 April 2032, the 25% charge could apply retrospectively.
- Applicable fund earnings: about A$60,000 (A$440,000 − A$380,000).
- Option A (no election): the A$60,000 is taxed at her marginal rate. The full A$440,000 counts as a non-concessional contribution, which exceeds her A$390,000 bring-forward cap by A$50,000.
- Option B (full election): her fund pays 15% on A$60,000, which is A$9,000. Only A$380,000 counts towards the cap, so it fits within the bring-forward limit. She can make no further non-concessional contributions until the 3-year period ends.
The point: timing, the election and the caps interact, and getting the order wrong can be costly.
Avoiding UK pension transfer scams
The FCA's ScamSmart guidance warns against cold calls, "free pension reviews", guaranteed or unusually high returns, early access before 55 and pressure to act quickly. Check UK firms on the FCA Register and Australian advisers on the Moneysmart Financial Advisers Register. Be wary of unusual overseas investments inside the new fund and of fees you can't see in writing.
UK expat pension advice in Melbourne: working across two systems
Most of the work is document-based and can be done by video, or in person at our Collingwood office near the CBD. Coordination matters more than location: your UK adviser, Australian adviser, accountant and, for an SMSF, auditor and lawyer each hold part of the answer. For property, residency and estate questions, see UK expat financial advice and the UK expat property checklist.
How AMGENT helps with a UK pension transfer to Australia
Advice begins by comparing transfer and non-transfer pathways, not by assuming a transfer should happen.
- What we advise on: Australian super and SMSF strategy, the receiving fund, caps, the earnings election, retirement income and estate planning. Ben is a qualified tax relevant provider.
- What we don't do: UK FCA-regulated transfer advice, UK tax returns or legal work such as SMSF deeds. We coordinate with specialists for these.
- Who advises: Benjamin (Ben) Waite CFP® has 25+ years in domestic and international financial markets, and his adviser profile lists transferring pensions and managing super efficiently among his focus areas.
- Fees: quoted in writing after the first meeting. Our Financial Services Guide (v02.26, issued 1 July 2026) lists initial advice fees of $3,500 to $22,000 including GST. UK adviser, SMSF and fund fees are separate.
AMGENT isn't independent. Our FSG explains that we may receive commissions on some life insurance products. You can read more about Ben and our approach.
UK pension transfer to Australia: FAQs
Can I transfer my UK pension to Australia?
Usually yes, if it's a funded UK pension, you're generally aged 55 to 74 (57 minimum from 6 April 2028), and the receiving fund is a QROPS. The State Pension and unfunded public service pensions can't be transferred.
Can I transfer my UK pension to Australia if I'm under 55?
Generally no. HMRC's pension age test means Australian funds that accept UK transfers must not pay benefits before 55, except for ill health. Most can only accept members who have reached that age.
Is there tax on a UK pension transfer to Australia?
Possibly on both sides. The UK's 25% overseas transfer charge applies unless an exclusion applies, such as being an Australian resident transferring to an Australian QROPS. In Australia, growth since you became a tax resident is taxable unless you transfer within six months.
Can I transfer my UK State Pension to Australia?
No. You can usually claim it while living in Australia, but it won't receive annual increases there.
Can I transfer my NHS, Teachers' or Police pension to Australia?
Generally no. Since 2015, UK rules prevent members of unfunded public service defined benefit schemes from transferring to schemes that offer flexible benefits, which includes Australian super.
Which Australian super funds are QROPS?
Those that have notified HMRC and still meet the ROPS conditions. HMRC's list is mostly SMSFs and isn't a guarantee of status, so confirm with the trustee.
How much of my UK pension can I move into super?
The transfer generally counts as a non-concessional contribution. For 2026–27 the cap is $130,000, or up to $390,000 under bring-forward if your total super balance was under $1.84 million at 30 June 2026. Any applicable fund earnings you elect to have taxed in the fund don't count.
Do I need a UK adviser to transfer my pension?
Yes, for safeguarded benefits such as a final salary pension worth more than £30,000. For other pensions it isn't compulsory, but advice on both sides is sensible.
Should I transfer my UK pension or keep it in the UK?
It depends on your guarantees, how long you'll stay, your age, caps, currency, fees and estate plans. UK pension income is generally taxable in Australia, while Australian super benefits are generally tax-free from 60.
Can AMGENT help with my UK pension transfer?
Yes, on the Australian side. We advise on super, SMSFs, tax (financial) advice, caps, retirement income and estate planning, and we coordinate with a UK FCA-authorised adviser where UK regulated advice is required.
Talk to a Melbourne adviser about your UK pension
Bring your UK pension statements, transfer values, residency dates and Australian super details to a free 30-minute discovery conversation. We'll help you work out whether a transfer is worth exploring and who needs to be involved.
Email info@amgentwealth.com.au · 88 Langridge Street, Collingwood VIC 3066